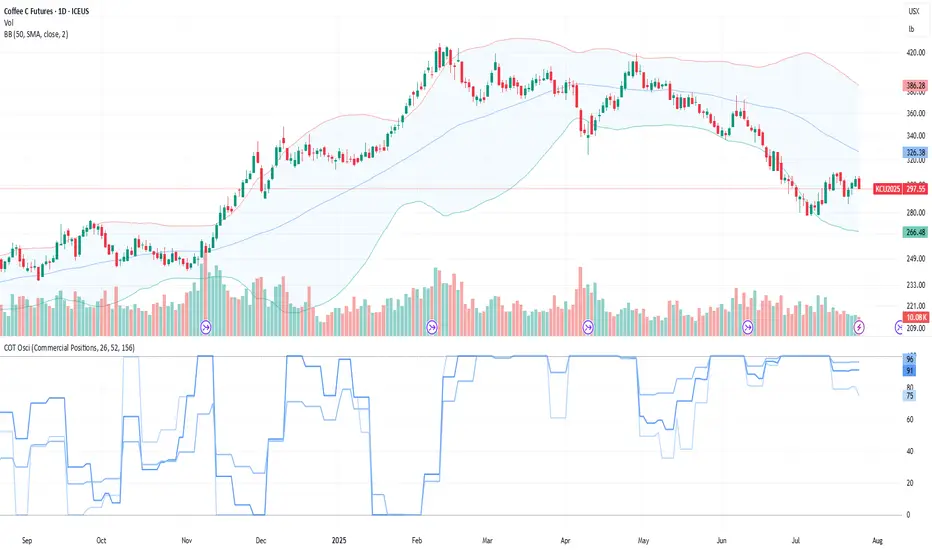
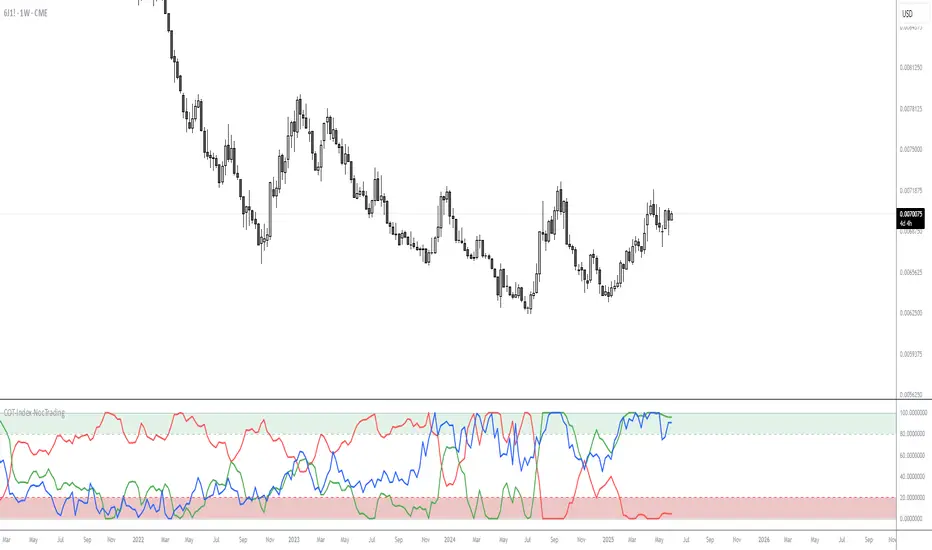
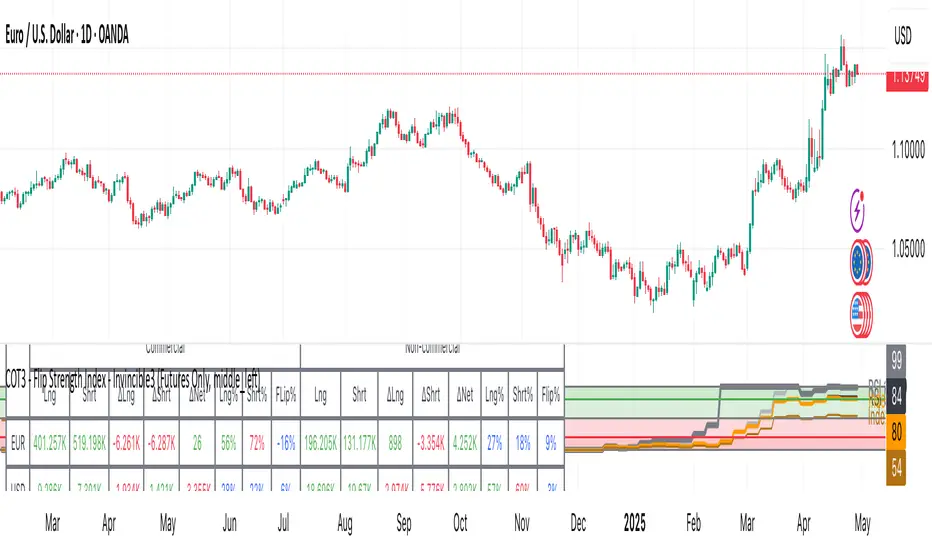
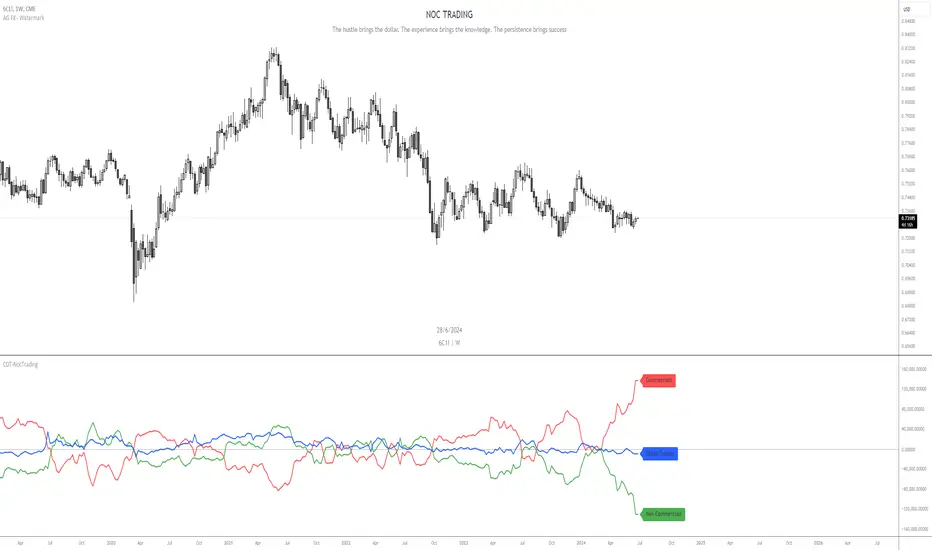
COT Index - Commercial Positioning (Weekly)Overview
This indicator helps futures traders identify relative Commercial Trader positioning extremes using weekly Commitment of Traders (COT) data from the CFTC.
How It Works
The script calculates Commercial Net Position each week:
Commercial Net Position = Commercial Long - Commercial Short
It then normalizes this value against its own recent history over a configurable lookback period:
COT Index = 100 * (Net Position - Lowest Net Position) / (Highest Net Position - Lowest Net Position)
Indicador